
By Iyoho IEmmanuel
ABUJA – The Presidency, BudgIT Foundation and Resource Justice Network (RJN), Nigeria, have called for urgent and coordinated efforts to close Nigeria’s huge energy financing gap, warning that the country’s ambitious energy transition plans will remain aunrealised unless policy commitments are translated into bankable projects and sustained investment.
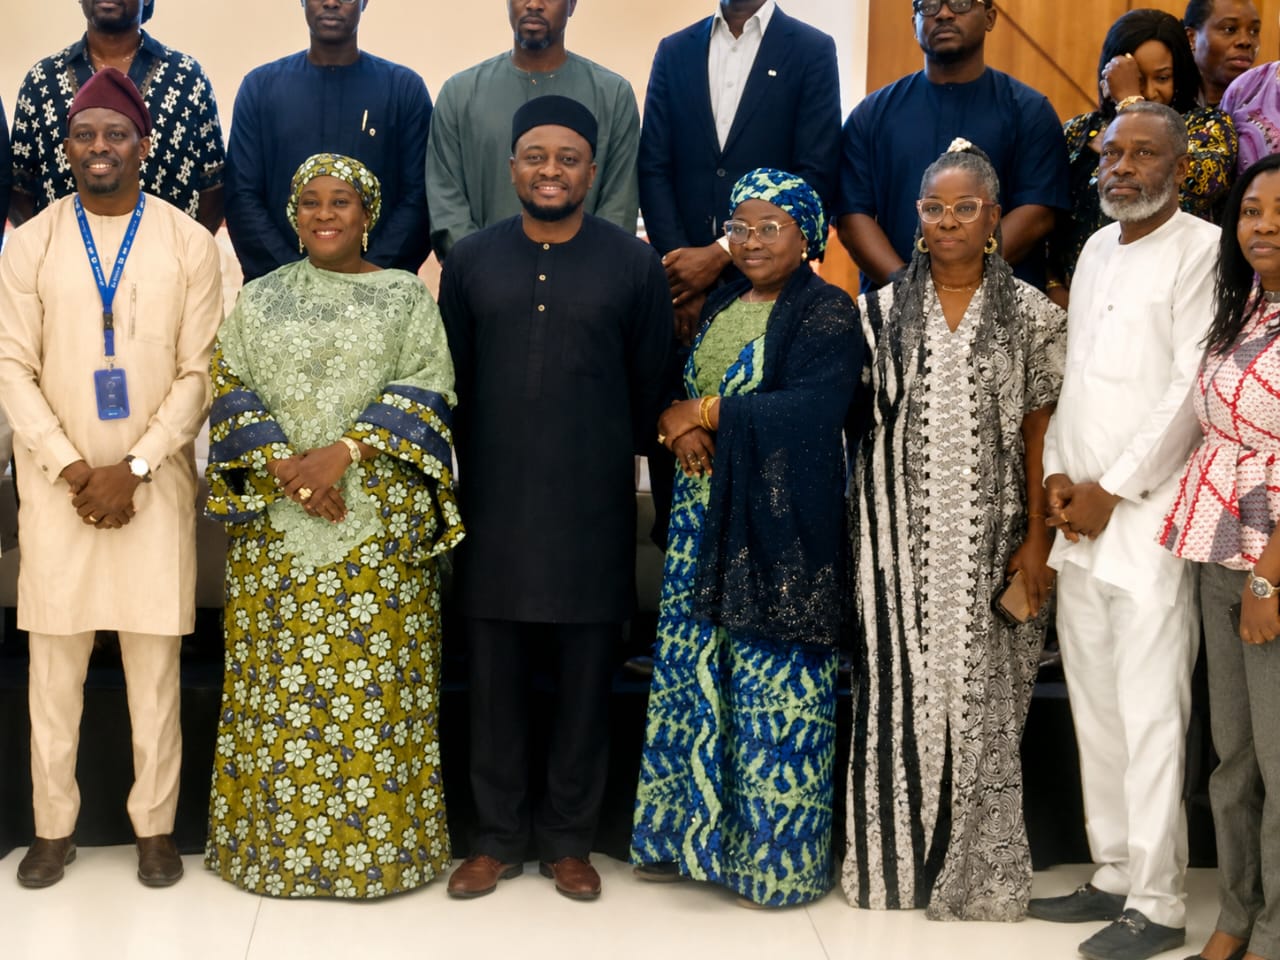
The stakeholders made the call at the Sustainable Energy Summit 2026 in Abuja, themed, “Financing Nigeria’s Energy Future: Closing the Gap Between Policy Commitment and Investment.”
Delivering the keynote address, the Senior Special Assistant to the President on Climate Finance and Stakeholder Engagement, Shelleng Ibrahim, disclosed that Nigeria would require about $1.9 trillion in total investment to achieve net-zero emissions by 2060, including approximately $410 billion above business-as-usual expenditure.
Ibrahim said the huge requirement should not be viewed merely as a financial burden but as one of the biggest investment opportunities in Nigeria’s history, with significant prospects in renewable energy, gas infrastructure, transmission and distribution, clean cooking, electric mobility, industrial energy efficiency, battery storage, green hydrogen and decentralised energy systems.
He said Nigeria had no shortage of energy policies, natural resources, entrepreneurial talent or investment opportunities, but lacked a reliable bridge between policy commitments and investable transactions.
“What we still lack is a sufficiently reliable bridge between policy commitments and investable transactions. That is the gap we must now close,” he said.
The presidential aide said the country’s energy future must simultaneously expand access, support economic growth and progressively reduce emissions, stressing that Nigeria could not pursue decarbonisation at the expense of development or sustain long-term prosperity with an energy system that remained expensive, unreliable and environmentally unsustainable.
According to him, the major obstacles preventing more capital from reaching Nigeria’s energy sector include inadequate project preparation, regulatory uncertainty, institutional fragmentation, high cost of capital, limited early-stage financing and financing structures that do not adequately reflect the different risk profiles of energy projects.
He explained that policy announcements alone could not constitute investment opportunities, as investors required feasibility studies, credible demand assessments, permits, land documentation, environmental safeguards, reliable financial models, clear revenue arrangements and mechanisms for managing risks.
Ibrahim consequently called for strong project-preparation facilities to help transform energy proposals into bankable projects capable of attracting investment.
He also urged the government to deploy public and concessional finance strategically to attract larger volumes of private capital, stressing that government could not and should not attempt to finance the energy transition alone.
He advocated the use of guarantees, first-loss facilities, viability-gap funding, interest-rate support and political-risk insurance to enable limited public resources to unlock multiples of private investment.
The presidential aide further called for deeper domestic financing for sustainable energy, saying projects that generate predominantly naira revenues should, wherever possible, be financed in naira.
He urged greater participation by pension funds, insurance companies, commercial banks, development finance institutions and the capital market, alongside the development of green bonds, sukuk, infrastructure funds and other financing instruments suitable for institutional investors.
Ibrahim also stressed the importance of policy stability, describing consistency and predictability in regulation as a form of capital.
“Policy consistency is itself a form of capital. When regulation is predictable, financing becomes cheaper. When institutions are coordinated, projects move faster,” he said.
He called for an inclusive energy transition that would benefit rural communities, women-led enterprises, young innovators and micro, small and medium-sized businesses, while urging Nigeria to build local capacity in engineering, component manufacturing, installation, maintenance, software, metering, energy management and battery recycling.
The BudgIT Foundation Country Director, Vahyala Kwaga, in his welcome address, said the summit had become necessary as global investment patterns continued to change, with investment in green energy growing rapidly while attracting capital to the traditional oil and gas sector became increasingly competitive.
Kwaga cited a 2026 study by the Natural Resource Governance Institute (NRGI), which found that total investment in clean energy grew tenfold between 2019 and 2024, while almost no capital went to Nigerian gas power during the period.
He said Nigerian firms received one-fifth of all African minigrid financing between 2019 and 2023, adding that Nigeria became the world’s fifth-largest recipient of international public finance for clean energy in 2023, receiving $829 million for 42 projects.
He further disclosed that Nigeria became the 10th-largest recipient of foreign investment for renewable energy in 2024.
Kwaga said the figures were significant against the backdrop of the increasing effects of climate change across the country, stressing that the decisions and actions taken at the present stage of Nigeria’s energy development would have far-reaching consequences for the country’s future.
“These are critical moments in Nigeria’s evolving history and the decisions and actions we take today have implications for our future. It is imperative we have honest and pragmatic conversations about these multiple issues to chart the right course for the country,” he said.
He explained that the Sustainable Energy Summit evolved from three years of engagements under BudgIT’s Energizing Sustainability Project, supported by the Resource Justice Network, with the organisation working alongside the Nigeria Coalition of the RJN and its long-standing partner, NRGI.
According to him, the initiative had promoted greater gender and youth inclusion in Nigeria’s climate discourse, while insights gathered from citizens across the country had been channelled into engagements with government institutions and private sector actors.
Kwaga said BudgIT had also, over the past decade, simplified and visualised 10 years of Nigeria Extractive Industries Transparency Initiative (NEITI) reports to make information on the country’s extractive sector more accessible to citizens.
He added that BudgIT had held four annual engagements with the Nigerian National Petroleum Company Limited to address concerns surrounding transparency and accountability.
In a goodwill message, the National Secretary of Resource Justice Network, Nigeria, Professor Helen Bodunde, said the country’s energy transition was ambitious but warned that aspirations must be matched with adequate investment.
Bodunde revealed that Nigeria’s Energy Transition Plan requires about $1.9 trillion by 2060, while the power sector attracts only about $1 billion annually against an estimated requirement of between $10 billion and $12 billion, leaving an annual financing shortfall of about $11 billion.
She said the underinvestment had contributed to more than 100 grid collapses over the past decade, undermining economic growth and public confidence in the electricity sector.
The RJN National Secretary also noted that while the removal of fuel subsidy in May 2023 had freed government resources, it had intensified economic pressure on citizens through higher transportation costs and inflation.
She, therefore ,called for the resources freed by subsidy removal to be channeled into clean energy investments capable of cushioning citizens and driving sustainable economic growth.
Bodunde also expressed concern over inadequate climate finance flows into Nigeria, noting that the country receives only about $2.5 billion annually, representing barely eight per cent of the estimated $29.7 billion required each year.
She, however, identified Nigeria’s sovereign green bonds as a positive indication of investor appetite, noting that the Series III sovereign green bond was oversubscribed by 183 per cent.
According to her, the successful green bond issuances demonstrated that investors were willing to support sustainable energy projects where governance was credible and projects were sufficiently bankable.
Bodunde urged government, the private sector and civil society to collaborate in scaling innovative financing mechanisms, including blended finance, public-private partnerships and climate-aligned financial instruments.
She also called for equitable access to clean energy, particularly for communities experiencing energy poverty, as well as greater investment in training and human capital development to equip Nigerians with the skills required for the clean-energy economy.
She stressed that communities must be direct beneficiaries of the energy transition, insisting that the process should create jobs, expand economic opportunities and improve livelihoods.
“Promises alone cannot power homes, industries or dreams. It is investment, courage and collaboration that will light the path forward,” Bodunde said.
The stakeholders agreed that Nigeria’s energy transition could not be achieved through government financing alone and called for stronger collaboration among public institutions, investors, development partners, civil society and communities.
They also urged stakeholders to move beyond conferences, policy announcements and financing pledges to actual transactions, construction and measurable results.
Ibrahim said the success of the country’s energy transition should ultimately be measured by the number of projects delivered, capital deployed, jobs created, businesses supported and communities provided with reliable, clean and affordable energy.
The stakeholders maintained that Nigeria possesses the natural resources, market, technology and entrepreneurial capacity required to build a sustainable energy future, but stressed that stronger institutions, predictable policies, innovative financing and effective project preparation would be crucial to unlocking the opportunity.